
Regain Financial Independence with 5 Steps to End Financial Enmeshment
By Maanya Nagpal
Five research backed steps to end family financial enmeshment. Use exact boundary scripts, safety actions for abuse, and PsyFi habit tools to keep your...
Financial enmeshment is when family members expect you to take on adult financial roles before you’re ready, or to keep funding theirs indefinitely, and the immediate step is to name and set one specific boundary rather than trying to fix the whole dynamic at once. If the pattern feels entrenched, a financial therapist, a neutral financial coach, or a structured behavioural tool like PsyFi can help you build the habit from there.
TL;DR:
Financial enmeshment often begins with small, repeated requests that involve inappropriate roles or obligations you are not emotionally or cognitively prepared for.
Recognizing signs such as secrecy, repeated bailouts, or managing family finances without formal role clarity is crucial for addressing enmeshment.
Setting clear, written boundaries before emotional conversations, and using concrete tools like boundary audits, helps re-establish independence from entangled family financial roles.
Breaking enmeshment involves both physical separation—like dissolving joint accounts—and relational work, such as repeated boundary-setting conversations.
If financial control patterns involve coerced debt, account restrictions, or withholding necessities, immediate safety measures and professional help are necessary to protect oneself.
Table of Contents
Recognising financial enmeshment: signs and family patterns to watch for
Setting and maintaining healthy financial boundaries with family
When it’s financial abuse: red flags and immediate safety steps
Real-life patterns: what financial enmeshment looks like in practice
Where professional help and behavioural tools fit into boundary work
A gentle option: using PsyFi to support the habit-change stage
Recognising financial enmeshment: signs and family patterns to watch for
Financial enmeshment rarely announces itself. It tends to show up as small favours that never stop being asked for.
Watch for parentification, where a child manages adult bills or mediates parental arguments about money well before they’re emotionally equipped to. Watch for secrecy, where one family member hides account balances or debts from a spouse or child who’s expected to help anyway. Watch for expected bailouts, where a relative assumes you’ll cover a shortfall as a matter of course, not a request. And watch for becoming the family’s financial confidant, the person everyone vents to but no one actually consults.
The line between helping and enmeshment usually comes down to two questions: is the request appropriate for your age and role, and is the relationship reciprocal.
You feel obligated rather than freely willing when the topic of money comes up.
The same person asks repeatedly, and refusal is treated as a betrayal.
You know more about a relative’s finances than they’ve formally shared with you.
Saying no has previously led to guilt, silence, or being labelled “selfish.”
If two or more of these feel familiar, the pattern is worth addressing directly rather than managing quietly.
How enmeshment shapes adult money habits and mental health
Financial enmeshment, as Creighton University researchers define it, happens when parents draw children into adult financial matters before they’re cognitively or emotionally ready. The same research ties that early parentification to anxiety, depression, under-employment, and weaker financial coping skills later in life. A mixed methods review of parentification confirms the pattern, finding small-to-moderate links between parent-focused parentification and depression and anxiety symptoms in adulthood.
Part of the mechanism is modelling, not just role reversal. Families with open, non-judgmental conversation about money tend to raise adults who manage credit and debt more capably, while Center for Retirement Research findings show that silence and emotional volatility around finances predict worse coping later on. Children absorb the emotional charge around money before they absorb any actual financial skill, which is one reason boundaries matter more than budgeting advice at this stage. Our piece on money mindset formation goes deeper into how these early patterns calcify into adult habits.
Setting and maintaining healthy financial boundaries with family
Boundaries work best when they’re specific, written down, and communicated calmly, not negotiated in the heat of a request.
Draft the rule before the conversation. Decide in advance: no more joint accounts, no cosigning, a fixed repayment schedule if you lend money, and a clear cap on what help you’ll give and how often.
Separate the financial housekeeping first. Open your own bank account if you haven’t, change shared passwords, and start monitoring your credit report independently.
Document any existing agreements. If money has already changed hands, put repayment terms in writing, even informally, so expectations aren’t relitigated later.
Pick a calm, private moment to talk. Avoid holidays, arguments, or the moment right after a request. Use “I” statements: “I can’t cosign this loan, but I can help you find other options.”
Expect pushback and hold the line anyway. Guilt, silence, or accusations of being selfish are common reactions when a long-standing system is disrupted, and consistency matters more than winning the first conversation.
Pro Tip: Write your boundary as a single sentence you can repeat verbatim under pressure, so you’re not improvising while someone else is upset.
A printable audit or worksheet helps here: list every recurring financial tie to family (shared accounts, informal loans, cosigned debt, bill splitting) and mark each one as “keep,” “renegotiate,” or “end.” That single document turns an abstract sense of unease into a concrete action list.
Financial therapists describe this work as separation-individuation rather than rejection: you’re establishing where your financial life ends and someone else’s begins, not punishing them for asking. Expect the first few boundary-setting conversations to feel harder than the actual financial change itself. Our guide on couples’ money communication has scripts that translate well to family conversations too.
When it’s financial abuse: red flags and immediate safety steps
Financial enmeshment and financial abuse can look similar from the outside, but abuse involves deliberate control, not just entangled habits. Watch for restricted access to your own accounts, being coerced into taking on debt, having necessities withheld, or having your employment sabotaged so you stay financially dependent, patterns Womenshealth as common tactics.
If any of these apply, prioritize safety over diplomacy. Make copies of your identification and financial documents and store them somewhere only you can access. Open an independent bank account, freeze or remove yourself from joint credit lines where possible, and check your credit report for accounts you didn’t authorize. National domestic violence hotlines, local shelters, and legal aid organizations can offer guidance specific to your situation and jurisdiction.
Real-life patterns: what financial enmeshment looks like in practice
Enmeshment rarely starts as a single dramatic event. It usually begins as one reasonable-sounding request that never gets revisited.
Consider a young adult who covers a parent’s phone bill during a rough month in their twenties. Ten years later, they’re still paying it, and any mention of stopping is met with “after everything I did for you.” The help was appropriate once. It became enmeshment when it stopped being reviewed.
Or consider a spouse who quietly manages their partner’s parent’s finances because “no one else in the family can handle it,” absorbing hours of unpaid labour and emotional stress that were never part of the marriage they signed up for. Or a teenager who becomes the household’s unofficial accountant during a parents’ divorce, translating bank statements and mediating custody-related expense disputes years before they’ve held a job themselves.
None of these situations involve a villain. They involve a boundary that was never set, and a role that quietly became permanent. Practitioners who work with these dynamics note that reversal usually requires two things at once: concrete changes like separating accounts, and relational work like scripts and repeated, calm boundary-setting. Neither alone tends to hold for long.

Where professional help and behavioural tools fit into boundary work
Different kinds of support solve different parts of this problem, and knowing which one you need saves time.
A financial therapist helps you understand the emotional and family-systems roots of the enmeshment itself, including guilt, loyalty binds, and inherited roles.
A neutral financial coach focuses less on the emotional history and more on structuring transactional rules, like documented repayment plans, that the whole family can follow.
A behavioural finance tool helps with the part that comes after insight and rules: actually practising the new habit daily until it’s automatic.
The realistic pathway is sequential: assessment of the pattern, a concrete boundary plan, then daily habit practice to make the new boundaries stick. Most people underestimate how much of the work happens in that last stage, long after the hard conversation is over. A family boundaries resource offers useful background on this transition for readers who want to go deeper on the family-systems side.
— Maanya
A gentle option: using PsyFi to support the habit-change stage
Once boundaries are set, the work shifts to daily practice, and a behavioural finance app can support this stage by linking accounts, tracking habits tied to new boundaries, and delivering real-time coaching based on individual patterns rather than generic advice. If old habits like covering a relative’s expenses on impulse start creeping back, PsyFi’s nudges are built to catch that in the moment. You can try the free Premium trial to see how daily tracking supports the boundaries you’ve already set.
Sources
Parents pass (bad) money habits to kids — Center for Retirement Research
Parentification vulnerability, reactivity, resilience, and thriving: A mixed methods review
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
What are the signs of enmeshment in families?
Common signs include a child or adult managing a parent’s finances, being expected to bail out relatives without question, and being treated as the family’s financial confidant despite having no formal role. Secrecy around money and one-sided financial obligation are also strong indicators, according to Creighton University’s research on the condition.
Is it possible to heal from family enmeshment?
Yes, though it typically requires both concrete changes, like separating accounts and documenting agreements, and relational work, like scripted boundary conversations repeated consistently over time. Financial therapists frame this as separation-individuation rather than rejection, and progress is usually gradual rather than immediate.
What are the signs of parental enmeshment with adult children?
Signs include a parent expecting ongoing financial support as routine rather than as an occasional favour, reacting to boundaries with guilt or accusations, and treating an adult child’s independent finances as still partly their own business. It often overlaps with a parent having raised that child in a parentified role earlier in life, per Creighton’s findings.
What are the signs that a spouse is enmeshed with a parent?
Warning signs include a spouse making financial decisions with a parent without consulting their partner, prioritizing a parent’s financial needs over the household’s, or feeling unable to say no to a parent’s requests regardless of the couple’s own financial situation. This often shows up as recurring tension over money that never fully resolves, since the underlying loyalty conflict, not the specific request, is the real issue.
How is financial enmeshment different from financial abuse?
Enmeshment involves entangled roles and unclear boundaries, often driven by loyalty or guilt rather than control. Financial abuse involves deliberate restriction of access to money, coerced debt, or sabotage, as described by womenshealth.gov, and calls for safety-focused action rather than boundary conversations alone.
Recommended
This content is provided for general informational and educational purposes only and does not constitute financial, investment, tax, or legal advice. PsyFi provides financial coaching tools and behavioral insights, not regulated advisory services. Always consult with a qualified financial advisor or tax professional regarding your personal situation before making financial decisions.
Keep reading
- Open One Account Today: Beat the Ostrich EffectResearch backed, low friction ritual to stop avoiding bills and accounts. Check one account today: do a two minute reflection, note four headline numbers,...
- Seven Gamified Savings Challenges Backed by Behavioral ScienceUse behavioral science to actually save: seven ready challenges, a 10 minute setup, and an app checklist to keep momentum without novelty burnout.
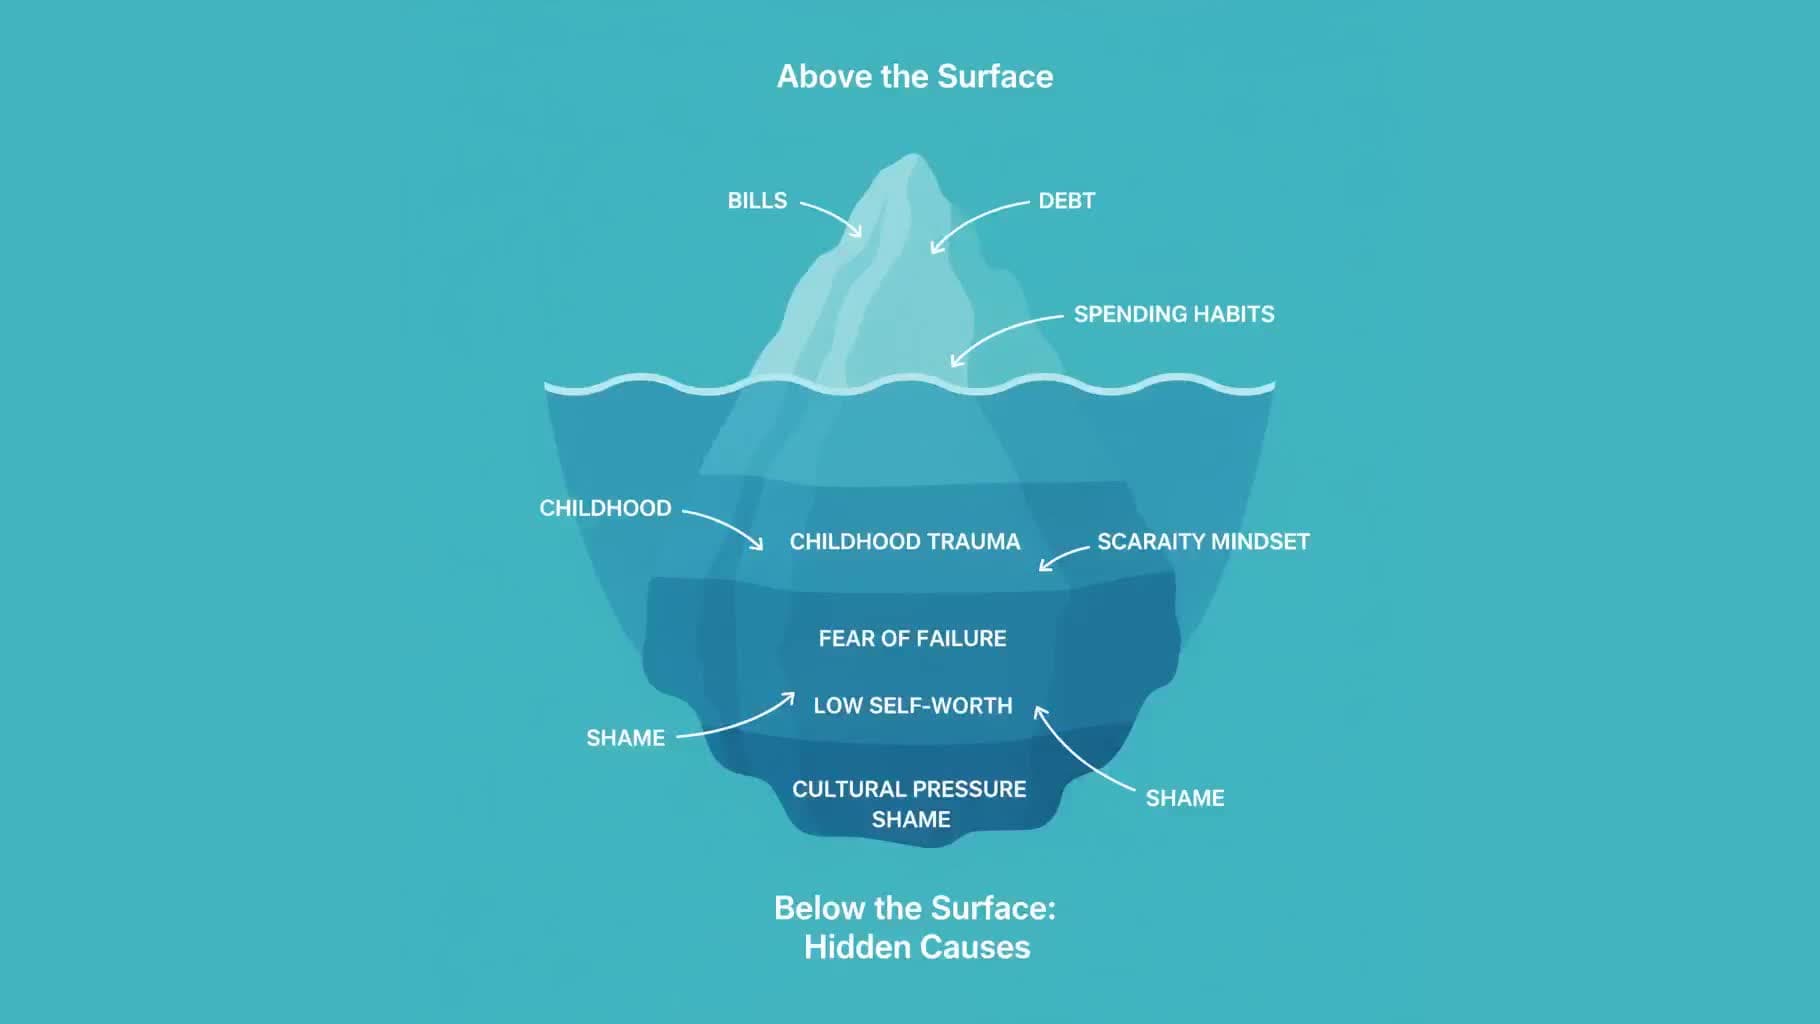
- The Financial Anxiety Iceberg: What You See vs. What's Really Happening