
Will You Sell in a Crash? Assess Risk Tolerance With 3 Goal Checks
By Maanya Nagpal
Discover if your asset allocation will survive a market crash by combining the sleep test, a risk quiz, and goal-specific stress testing.
Yes, you should assess your risk tolerance now, and you can do it properly in under 10 minutes using three checks: a quick self-check (the “sleep test”), a short questionnaire, and a simple stress test on your biggest goal. Take a risk tolerance quiz first, then run a real-dollar downturn scenario against your top goal to see if the score actually holds up.
TL;DR:
Run a realistic dollar-based stress test to verify if your risk tolerance score holds up during a severe downturn over several months.
Ensure your ability, willingness, and need align, especially for short-term goals or if your emergency fund is inadequate, before accepting a certain asset allocation.
A 70/30 portfolio typically leads to significant paper losses in a bear market, requiring diversification, rebalancing, and liquidity buffers to manage downturns.
Use a stress test combined with a risk quiz; if answers significantly differ, prioritize your financial ability, such as time horizon and income stability, over subjective confidence.
Continuously track behavioral signals like checking frequency and emotional reactions to market dips, and reassess your risk plan after major life events or persistent discrepancies.
Psyfiapp
Build Better Investing Habits
PsyFi uses behavioral science and actual financial data to provide personalized saving and investing insights as your habits evolve.
Table of Contents
What’s the difference between ability, willingness and need?
How do you stress-test your risk tolerance before you commit?
How do you assess risk tolerance with a quick self-check?
Before you touch a questionnaire, run the sleep test. Investor.gov frames this as choosing investments you can actually hold onto when they lose value, not just ones that look good on paper — because balancing your ability and willingness to take risk is the whole point of the exercise. Picture your portfolio dropping 20% in a month. If that’s $100,000, you’re staring at an $80,000 balance. Would you check your account daily, call your advisor in a panic, or sell? Your honest answer is worth more than any quiz score.
Pair that gut check with a quick liability audit for each goal. Note:
Time horizon: years until you need the money for this specific goal
Emergency fund size: months of expenses covered outside your investments
Near-term liabilities: any debt, tuition, or big purchase coming in the next 1 to 3 years
Goals under five years should lean conservative regardless of how you feel about risk, since time horizon is one of the clearest drivers of appropriate asset allocation. A thin emergency fund or heavy near-term liabilities push you conservative too, even if your gut says “aggressive.” Once you’ve got answers for each goal, label it: conservative, moderate, or aggressive. That label is your starting point for everything that follows.
What do risk tolerance quizzes actually measure?
Most quizzes lean on the same building blocks: loss scenarios (“how would you react if your portfolio dropped 15%?”), trade-off questions (higher potential return versus more volatility), and time-horizon items (when do you need this money?). U.S. Bank’s guidance boils this down to a short set of six practical questions covering goals, time horizon, comfort with loss, checking frequency, savings buffer, and diversification.
Score bands typically land you in a bucket:
Conservative (low tolerance for loss, short horizon or high liquidity needs)
Moderate (some tolerance for volatility, mid-length horizon)
Aggressive (high tolerance for loss, long horizon, stable income)
Treat that bucket as a hypothesis, not a verdict. Quizzes measure how you think you’ll react, not how you behave when your phone buzzes with a market alert. Confidence and knowledge aren’t the same thing. Higher subjective confidence can inflate your self-reported tolerance, and financial knowledge moderates how accurately risk tolerance is measured. A person who feels sure of themselves can score “aggressive” while knowing very little about how bear markets actually feel.
Pro Tip: Run a quiz twice, once on a calm day and once right after reading bad market news. If your answers shift a lot, your true tolerance is probably closer to the lower score.
What’s the difference between ability, willingness and need?
Any quiz score means little until you run it through this framework, which practitioner guides consistently point to when assessing risk tolerance properly.
Ability: what your circumstances allow. A 30-year-old with stable income and a 30-year horizon has high ability, even if they feel nervous about markets.
Willingness: your emotional comfort with loss, best measured through the sleep test rather than abstract questions.
Need: the return required to actually hit your goal. If you need 8% annually to retire on schedule, “playing it safe” at 3% guarantees you miss the target.
Mismatches are common and instructive. High ability plus low willingness (a young, well-paid saver who panics at every dip) usually means: build a portfolio your ability supports, but automate it so willingness never gets a vote during a downturn. Low ability plus high willingness (someone five years from retirement who says they’re fine with volatility) is the riskier mismatch. Ability should generally win that argument.
What does a 70/30 portfolio actually mean for you?
A 70/30 split, 70% stocks and 30% bonds, is a moderately aggressive stance built to grow faster than inflation while cushioning some of the swings. Stocks drive long-term growth and short-term volatility. Bonds dampen the ride and provide income, though they rarely keep pace with equities over decades.
Here’s what that actually feels like in a downturn: if your portfolio holds a 70/30 mix during a severe bear market, the equity portion can lose a substantial part of its value while bonds tend to hold steadier. This leads to a significant paper loss on the whole portfolio. Nothing about that number is wrong. It’s simply the price of the long-term growth 70/30 is designed to deliver, and it’s exactly the scenario the sleep test should have already prepared you for.
A few rules keep that split working as intended:
Diversify within each slice (broad index exposure, not five overlapping tech funds)
Rebalance on a set schedule, not based on headlines
Keep a separate cash reserve so you’re never forced to sell equities at the worst moment
Our asset allocation by age guide walks through how these splits typically shift as your horizon shortens.
How do you stress-test your risk tolerance before you commit?
A quiz score is a hypothesis. A stress test is the experiment that checks it. Project your target portfolio month by month through a realistic bear-market drawdown, using your actual dollar amounts, not percentages in the abstract. Watch the balance fall for three, six, nine months. At each stage, ask what you’d actually do: check the account more often, feel your stress rise, or want to sell.
That behavioural layer matters more than the number itself. Combining a questionnaire with a simple, real-dollar stress test exposes gaps a quiz alone can’t catch, and empirical work backs this up: psychometric scores align reasonably well with self-reported tolerance but hold up better when validated against actual behaviour rather than taken at face value.
Track your own checking frequency and emotional response during volatile weeks. PsyFi’s financial stress score is built for exactly this: it turns those behavioural signals into a number you can watch over time, instead of guessing after the fact whether you handled a dip well or badly.
Pro Tip: If you catch yourself checking your portfolio more than once a day during a decline, that’s a behavioural red flag, not just a habit. It usually means your actual willingness is lower than your quiz score suggested.
What should you do after you know your risk tolerance?
Once your self-check, quiz score, and stress test roughly agree, act on it.
Set your target allocation and write it down, so future-you has something to check current decisions against.
Top up your emergency fund first if the stress test revealed thin liquidity. This removes pressure to sell investments during a downturn.
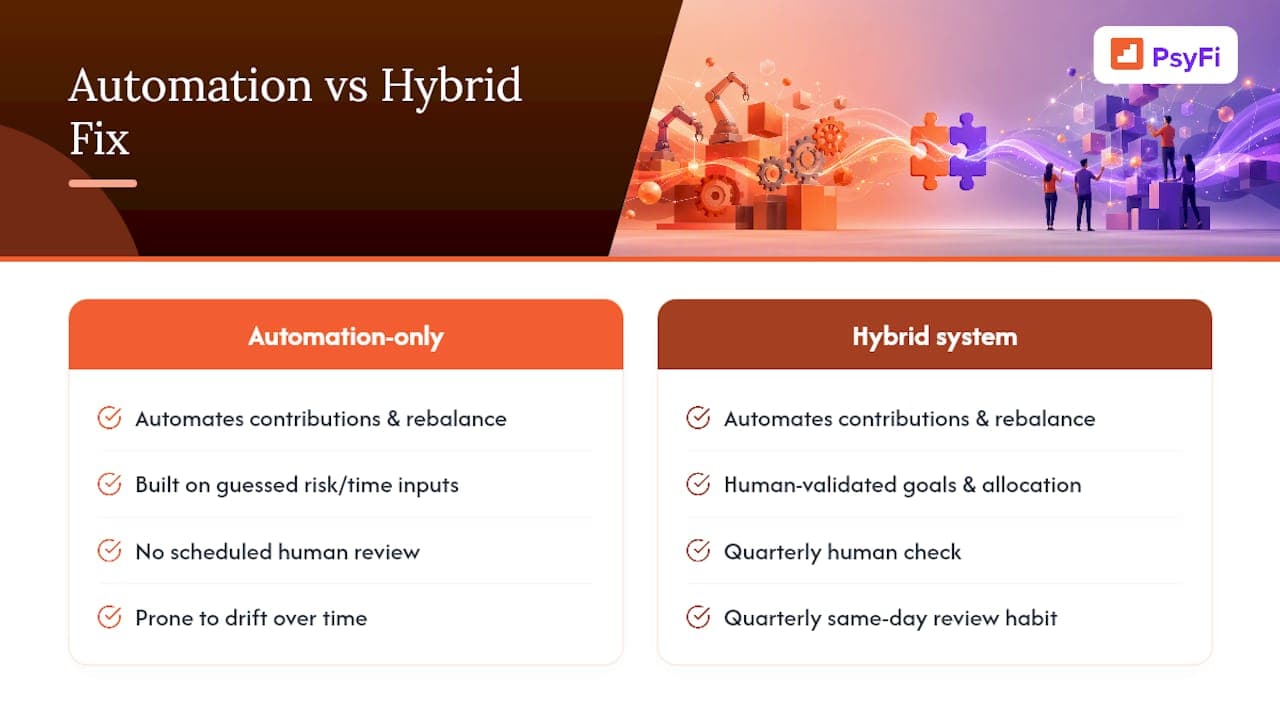
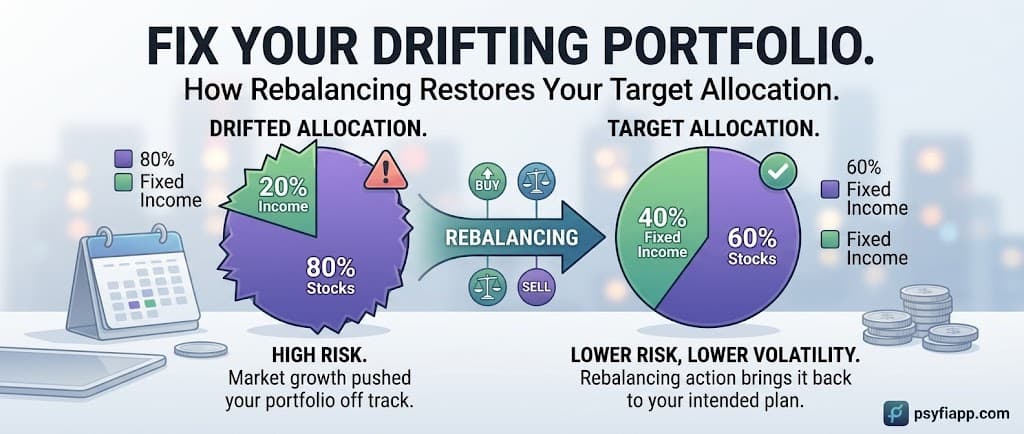
Set rebalancing rules (annual, or when any asset class drifts 5 percentage points from target) so decisions aren’t made in the heat of a bad week.
Log your reactions during real volatility. Note checking frequency, stress level, and any urge to deviate from the plan.
Reassess annually, and immediately after major life events: a new job, marriage, a child, nearing retirement, or a market crash that tested your nerve for real.
If your stress test consistently disagrees with your quiz score, or a major life change just hit, that’s the moment to talk to a fee-only advisor rather than adjust alone. Ask them directly how they’d handle a repeat of a 2008 or 2020 style drawdown with your specific goals. And if anyone pitches a plan promising high returns with low risk, treat it as a warning sign; Investor.gov flags that exact combination as one of the clearest signs of fraud.
Watching the framework play out
A reader once described running the sleep test on a $150,000 portfolio and realizing a 20% drop would genuinely keep them up at night, despite scoring “aggressive” on a quiz. The stress test confirmed it: by month four of a simulated downturn, the urge to sell was strong. The fix was a shift to 60/40 and a standing rebalancing rule, reviewed every January and after any month with a double-digit drawdown.
— Maanya
How PsyFi turns risk assessment into an ongoing habit
A quiz score and a one-time stress test are a solid start, but risk tolerance isn’t static. It shifts with income, life events, and how markets have treated you lately. PsyFi’s behavioural finance engine tracks the signals that matter after the initial assessment: how often you check your accounts, how you react to volatility, and whether your actual spending and saving habits still match the plan you set.
Start with the financial literacy quiz to check your objective financial knowledge against your confidence level, since the two don’t always match. From there, PsyFi’s financial stress score gives you a running behavioural read instead of a one-time snapshot, and the platform’s free calculators help translate whatever you learn into a concrete savings and investing plan. If you’re ready to see how your current habits stack up against your stated risk tolerance, try PsyFi and start the free trial today.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
FAQ
How do I calculate my risk tolerance?
Combine a short questionnaire score with the sleep test and a real-dollar stress test on your largest goal; where the three disagree, weight your financial ability (time horizon, income stability, liquidity) most heavily.
What risk tolerance is 70/30?
A 70/30 stock-to-bond split reflects a moderately aggressive profile built for growth over a longer time horizon, with enough bonds to soften, but not eliminate, downturn swings.
Can you give me an example of risk tolerance?
Someone with a 25-year horizon and stable income might comfortably hold 80% stocks, while someone retiring in two years with the same quiz score should hold far less equity because their time horizon and need for stability differ.
What are the three types of risk tolerance?
Most frameworks group investors as conservative, moderate, or aggressive, based on how much short-term loss they can absorb financially and emotionally while still staying invested toward their goal.
Recommended
2026 War Crash: How to Invest in VEQT, XEQT, ZEQT, HEQT, TEQ
Why You Should Not Direct Deposit Your Paycheque Into Crypto
This content is provided for general informational and educational purposes only and does not constitute financial, investment, tax, or legal advice. PsyFi provides financial coaching tools and behavioral insights, not regulated advisory services. Always consult with a qualified financial advisor or tax professional regarding your personal situation before making financial decisions.
Keep reading
- Stop Drift: Rebalancing Plan for Most Investors, Annual or SemiannualPick a rebalance schedule you’ll actually follow: annual or semiannual reviews for most investors, add a 5% or 200/175 threshold for larger accounts, and...
- Seven Gamified Savings Challenges Backed by Behavioral ScienceUse behavioral science to actually save: seven ready challenges, a 10 minute setup, and an app checklist to keep momentum without novelty burnout.