
Four Stages to Recover From Financial Trauma: Start With Safety
Recover from financial trauma with a safety first, four stage plan. Learn evidence based therapies, simple routines, and low pressure tools to rebuild.
Financial trauma is a lasting psychological response to repeated or extreme money-related harm that rewires how your body and mind respond to money. If symptoms are interfering with your sleep, work, or relationships, the first priority is emotional safety and, where needed, professional support. Practical financial fixes come second, and they work far better once the nervous system is no longer in survival mode.
TL;DR:
Deeply ingrained financial trauma stems from repeated or severe harm, causing the nervous system to respond with threat signals even in stable financial situations.
Trauma symptoms often include panic, shame, avoidance, physical pain, and interference with daily functioning, especially if lasting more than two weeks.
Early childhood experiences like scarcity or financial abuse lay the groundwork for adult trauma, making practical fixes ineffective until underlying threat responses are addressed.
Recovery requires a staged approach prioritizing emotional safety, re-establishing routines, and seeking therapy before attempting budgeting or financial planning.
Support tools like breathing exercises, small automated savings, and professional therapy significantly improve outcomes when combined with trauma-informed care.
Table of Contents
What financial trauma is and how it’s different from everyday stress
A staged recovery plan for rebuilding after financial trauma
What financial trauma is and how it’s different from everyday stress
Everyday financial stress is situational. A surprise bill or a tight month raises your heart rate for a while, then fades once the problem is solved. Financial trauma is different: it is a lasting imprint left by repeated or severe money-related harm, and it keeps activating your threat response even when your current finances are stable.
Clinically, what separates the two is duration, intensity, and the involvement of the nervous system’s survival circuitry. A single bounced cheque is stressful. Years of unpredictable income, coercive control over shared money, or a sudden bankruptcy can condition your brain to treat any financial task, even opening an app, as a threat cue. This is why trauma-informed care frameworks emphasize restoring a felt sense of safety and trust before asking someone to change behaviour.
Common experiences that tend to produce trauma-level responses include:
Growing up in a household where money scarcity was chronic and unpredictable.
Living through financial abuse, where a partner controlled or withheld access to funds.
Experiencing a sudden, severe loss such as bankruptcy, foreclosure, or a major medical debt.
Being repeatedly harassed by debt collectors or facing eviction threats.
This distinction explains why budgets alone often fail for people with this history. A spreadsheet cannot calm a nervous system that has learned to associate a bank balance with danger. Until the underlying threat response is addressed, even a well-designed budget tends to trigger avoidance rather than follow-through.
Signs and symptoms to recognize in yourself
Financial trauma shows up across four domains, and most people notice symptoms in more than one at a time. Recognizing the pattern is often the first step toward taking it seriously rather than dismissing it as poor discipline.
Emotional and cognitive signs: shame or panic when checking your balance, racing thoughts about worst-case scenarios, and trouble concentrating on anything money-related.
Behavioural patterns: avoiding mail and banking apps, compulsive spending as a short-term relief valve, or hoarding cash even when bills are unpaid elsewhere.
Physical consequences: disrupted sleep, stomach issues, tension headaches, or a racing heart triggered by financial reminders.
Functional impairment: symptoms that interfere with work, relationships, or basic daily routines.
A significant share of young adults facing high financial stress report a markedly higher likelihood of severe psychological distress, according to a study using pooled national health survey data. That gap illustrates how financial strain does not stay contained to a bank account; it spills into mental health in ways that are measurable and significant.
The clinical threshold worth knowing: according to the National Institute of Mental Health, symptoms such as hopelessness, tearfulness, irritability, or trouble concentrating that persist for more than two weeks are a signal to consult a mental-health professional. If that describes your last few weeks, this is not a discipline problem. It is a signal worth acting on.
Causes and how early experiences shape adult money habits
Financial trauma rarely comes from a single event. More often it is built from repeated exposure to scarcity, sudden shocks, or coercion, layered onto beliefs formed long before adulthood.
Children raised in unpredictable financial environments develop heightened threat detection: the brain learns to scan for danger because scarcity itself was dangerous. That wiring does not switch off simply because income later stabilizes. It shows up as hypervigilance around spending, or the opposite: a shutdown response where looking at money feels unbearable.
These early experiences also produce what financial psychologists call money scripts, automatic and often unconscious beliefs about what money means. Recurring patterns include money avoidance, money vigilance, money worship, and money status, each formed in childhood and carried, largely unexamined, into adult decisions. Our own explainer on understanding your money mindset walks through how these scripts get formed and how to start noticing yours.
Pathways to financial trauma commonly include:
Chronic childhood scarcity, where basic needs were uncertain or conditional.
Financial abuse, where a partner restricted access to accounts or information.
A sudden major loss, such as bankruptcy, job loss, or a medical debt spiral.
Prolonged harassment from debt collectors or the threat of losing housing.
Each of these pathways trains the nervous system to treat money as a source of danger rather than a neutral tool, which is precisely what later makes practical fixes feel so hard to sustain.
How financial trauma affects your body and daily life
When the nervous system perceives a financial threat, it does not distinguish between an actual emergency and a stressful email from a collections agency. Both can trigger the same fight, flight, or freeze response: elevated cortisol, a racing heart, and a narrowed capacity for the kind of calm, forward-looking thinking that budgeting requires.

Sustained activation of that response has consequences beyond the moment. Consumer financial well-being has declined in recent years, and a large share of households reported they could not cover a month of expenses if their income stopped, according to the Consumer Financial Protection Bureau’s Making Ends Meet survey. That kind of precarity keeps the threat response switched on for long stretches rather than allowing it to resolve.
Over time, this shows up as chronic fatigue, disrupted sleep, weakened concentration at work, and strain in relationships, since financial stress is consistently ranked among the top sources of stress for adults, and avoidance of the topic tends to make outcomes worse rather than better, according to the American Psychological Association. None of this means you are failing to cope. It means your body is doing exactly what a threatened nervous system is built to do.
When to seek professional help or crisis support
Some symptoms call for more than self-help. Knowing the line between “this is hard” and “this needs support” can save weeks of unnecessary suffering.
Seek a mental-health professional if hopelessness, irritability, tearfulness, or trouble concentrating persists for more than two weeks, per NIMH guidance.
Treat thoughts of self-harm, or a sense that you cannot cope at all, as an immediate crisis: contact a crisis line or emergency services without delay.
SAMHSA’s crisis and disaster resources apply to severe financial shocks as well as other emergencies, and are built around safety, trust, and empowerment.
If debt collectors are a major source of distress, you have a right to file a complaint with the CFPB, which can reduce harassment and lower one concrete source of ongoing threat.
Reducing external pressure, such as collector contact, is not a side issue. It removes one of the triggers keeping your nervous system on alert, which makes every other step in recovery easier.
Treatments and coping strategies that actually help
The most credible path out of financial trauma combines two kinds of work: psychological treatment that addresses the nervous system and the beliefs driving avoidance, and practical routines that slowly rebuild a sense of control. Neither alone tends to hold.
Cognitive behavioural therapy (CBT): considered a gold-standard treatment for anxiety, CBT helps identify and change the automatic thoughts and money scripts that drive avoidance or compulsive spending.
Trauma-informed psychotherapy: rather than jumping straight to budgeting, this approach prioritizes safety and pacing, which reduces the risk of retraumatization when money topics resurface.
Financial therapy: a hybrid discipline that pairs financial planning with therapeutic technique, useful when the emotional charge around money is too high for a planner alone but the issue is not purely clinical either.
Short-term emotion-regulation tactics: slow breathing, grounding exercises, and journalling before opening a bill or a banking app can reduce the flood of anxiety enough to think clearly, and journalling specifically has been shown to support this kind of emotional processing.
Two-pronged recovery, pairing psychotherapy with incremental financial routines, tends to work better than either approach alone, since it addresses both the reprocessing of belief and threat responses and the practical rebuilding of a sense of mastery, according to an American Psychological Association discussion of financial wellness. That sequencing matters: trying to fix the budget before calming the nervous system usually backfires, producing another wave of avoidance instead of progress.
Talking with a trusted friend, a support group, or a therapist about the emotional weight of money, separate from the numbers themselves, is itself a valid and evidence-supported coping step. Avoidance is a predictable response to financial threat, not a character flaw, and therapy works in part by replacing avoidance with small, tolerable exposures to the thing that feels dangerous.
Pro Tip: Before opening a banking app or a bill, take three slow breaths and name one thing in the room around you. That brief pause interrupts the threat response enough to let you read the numbers instead of just reacting to them.
A staged recovery plan for rebuilding after financial trauma
Recovery goes faster and sticks better when emotional safety work is separated from financial tasks. Trying to do both at once is what usually triggers a shutdown or a spending spiral.
Stage 1, safety: build a tiny daily routine, such as a two-minute breathing practice or a short walk, that has nothing to do with money and simply tells your nervous system it is not in danger right now.
Stage 2, triage: address only the most urgent payments (housing, utilities, essential debts), and where collector contact is a major stressor, use your right to file a complaint to reduce harassment.
Stage 3, routine building: introduce a five-minute daily or weekly money check, set up small sinking funds for predictable expenses, and automate transfers so decisions happen less often and with less emotional load.
Stage 4, rebuilding: begin financial therapy or CBT if symptoms persist, and start building a cushion against future income shocks once the basics feel steady.
This order matters more than the specific tools you use. Safety first, then triage, then routine, then long-term rebuilding, each stage makes the next one possible instead of overwhelming.
Pro Tip: Automate one small transfer, even $5, into a sinking fund this week. The goal at this stage is not the amount. It is proving to yourself that a financial action can happen without triggering a spiral.
Why ‘just budget’ advice misses the point
Most financial advice assumes a calm nervous system and a blank slate, and that assumption is exactly why it fails so many people. A budget template cannot account for the fact that opening a spreadsheet might trigger the same threat response as the original event that caused the trauma. Telling someone with financial trauma to “just track their spending” is a bit like telling someone with a fear of heights to “just look down”: technically actionable, practically useless without addressing the underlying response first.
What actually works is smaller and slower than most advice admits: a breathing exercise before a bill, a five-minute check-in instead of a full audit, a therapist who understands money shame instead of only spreadsheets. Technology can support this work by making small routines easier to sustain and by giving people a way to see progress without reopening old wounds every time. It is not a replacement for therapy, but it can be a steady companion to it.
— Maanya
Tools that can support your recovery plan
If you are working through the stages above, a few low-pressure tools can help without adding pressure. PsyFi’s free financial stress score gives you a starting measure of where you stand emotionally around money, which is useful before you touch a single number in your budget. The financial anxiety cost calculator shows what avoidance has actually been costing, which can motivate Stage 3 routines without shame attached. Pair either with the app’s real-time coaching, available through Premium Monthly at $9.99 per month, to get personalized nudges as you rebuild.
This article is general information, not a substitute for advice from a qualified doctor. Consult a qualified healthcare professional about your own circumstances before acting on anything here.
Sources
Financial stress and psychological distress among young adults (study)
Disaster preparedness, response, recovery, and mitigation | SAMHSA
FAQ
What are the symptoms of financial trauma?
Financial trauma shows up as shame or panic around money, avoidance of bills or banking apps, compulsive spending or hoarding, and physical signs like disrupted sleep or headaches. According to NIMH, symptoms persisting beyond two weeks, or interfering with daily life, are a signal to seek professional support.
How to fix financial trauma?
Recovery works best in stages: start with emotional safety routines, then triage urgent payments, then build small financial habits, then pursue longer-term work like CBT or financial therapy. Cognitive behavioural therapy is considered a leading treatment for the anxiety patterns that often underlie financial trauma.
Why am I so stressed about money all the time?
Persistent money stress often reflects a nervous system conditioned by past financial harm, not a personal failing, and money is consistently one of the top reported stressors for adults according to the American Psychological Association. Avoidance is a common coping response that tends to make the stress worse over time rather than better.
What can I do to reduce financial stress right now?
Short-term relief comes from grounding techniques such as slow breathing or journalling before facing a bill, paired with small, automated financial routines that reduce how often you have to make a decision under stress. If collector harassment is a factor, filing a complaint with the CFPB can remove one active source of pressure.
What is the difference between financial stress and financial trauma?
Financial stress is a situational reaction that fades once a problem resolves, while financial trauma is a lasting change in how your nervous system responds to money, often rooted in repeated or severe past harm. The clinical marker to watch for is duration and functional impairment: symptoms lasting more than two weeks or interfering with daily life point toward trauma rather than ordinary stress, per NIMH.
Recommended
This content is provided for general informational and educational purposes only and does not constitute financial, investment, tax, or legal advice. PsyFi provides financial coaching tools and behavioral insights, not regulated advisory services. Always consult with a qualified financial advisor or tax professional regarding your personal situation before making financial decisions.
Keep reading
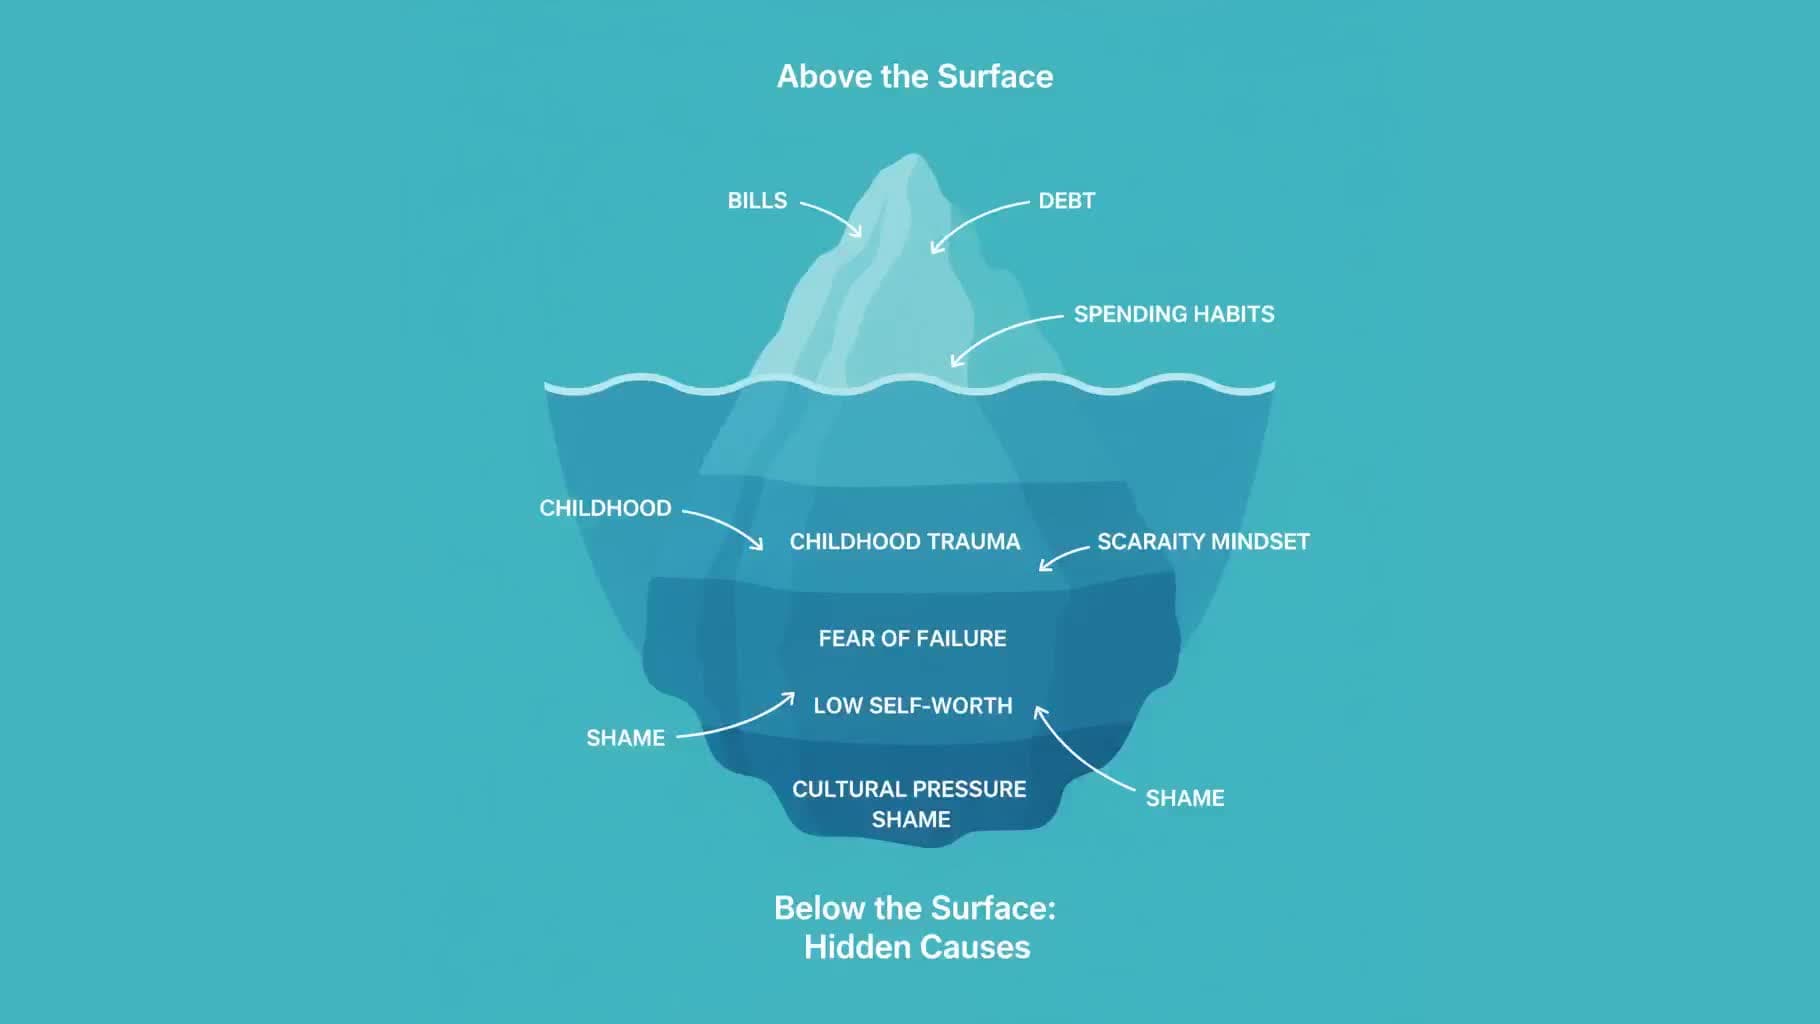
- The Financial Anxiety Iceberg: What You See vs. What's Really HappeningUnderstanding financial stress isn't just about looking at bank balances; it's about recognizing the hidden psychological forces beneath the surface. Like an iceberg, where only 10% is visible above water while 90% lurks below, financial anxiety reveals itself through obvious symptoms while its deepest causes remain hidden from view. We at PsyFi think that finding the root psychological causes of money stress is the key to achieving financial wellness.
- Open One Account Today: Beat the Ostrich EffectResearch backed, low friction ritual to stop avoiding bills and accounts. Check one account today: do a two minute reflection, note four headline numbers,...
- Applied Behavioral Economics in Personal Finance: How AI Micro-Interventions Reduce Intention-Action Gap FailuresMost budgeting tools assume rational actors. Early PsyFi beta data suggests psychology-first micro-interventions and daily AI check-ins close the intention-action gap better than end-of-month reviews.